Банковские системы: России, Америки, Британии
England, Bank of
The Bank of England was incorporated by act of Parliament in 1694 with the immediate purpose of raising funds to allow the English government to wage war against France in the Low Countries (see). A royal allowed the bank to operate as a joint-stock bank with limited liability. No other joint-stock banks were permitted in England and Wales until 1826. This special status and its position as the government's banker gave the bank considerable competitive advantages.
The bank was located first in Mercers' Hall and then in Grocers' Hall, but it was moved to its permanent location on Threadneedle Street in the 1730s. By that time it had become the largest and most prestigious financial institution in England, and its bank notes were widely circulated. As a result, it became banker to other banks, which, by maintaining balances with the Bank of England, could settle debts among themselves. The bank was threatened by the economic instability that accompanied the, but its standing was also considerably enhanced by its actions in raising funds for Britain's involvement in those conflicts.
During the 19th century the bank gradually assumed the responsibilities of a central bank. In 1833 it began to print legal tender, and it undertook the roles of lender of last resort and guardian of the nation's gold reserves in the following few decades.
The bank was privately owned until 1946, when it was nationalized. It funds public borrowing, issues bank notes, and manages the country's gold and foreign exchange reserves. It is an important adviser to the government on monetary policy and is largely responsible for implementing the chosen policy by its dealings in the money, bond, and foreign exchange markets. The bank's freedom of action in this regard was considerably enhanced when it was given the power to determine short-term interest rates in 1997
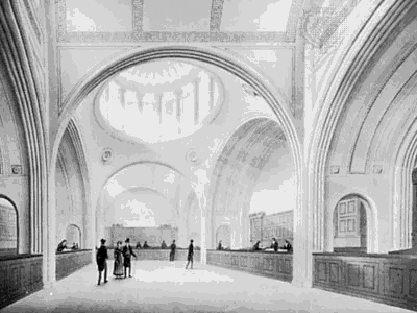
The
Colonial Office in the Bank of England,
unsigned watercolour by one of Sir John Soane's draftsmen, c. 1818;
in Sir John Soane's Museum, London.
By courtesy of the trustees
of Sir John Soane's Museum, London; photograph, R.B. Fleming
The Bank of Russia.
The tasks and functions of the Bank of Russia are set by the
Constitution of the Russian Federation and Federal Law on the Central
Bank of the Russian Federation (Bank of Russia). The Bank of Russia’s
main objective is to protect the rouble and ensure its stability. The
Bank of Russia is also the sole issuing centre and the body of
banking regulation and supervision. Its main functions are formulated
in Article 4 of the Federal Law on the Central Bank:
- in
collaboration with the government of the Russian Federation, it
elaborates and implements a uniform national monetary policy designed
to protect the rouble and ensure its stability;
- it is the only
issuer of cash and the organiser of its circulation;
- it is the
creditor of last resort for credit organisations and organises the
refinancing system;
- it sets the settlement rules of the Russian
Federation;
- it sets the rules of conducting banking operations
and accounting and the reporting rules for the banking system;
-
it conducts state registration of credit organisations and issues and
revokes the licences of credit organisations and the organisations
that audit them;
- it supervises the activities of credit
organisations;
- it registers the issue of securities by credit
organisations in accordance with federal laws;
- it conducts, on
its own behalf or on behalf of the government of the Russian
Federation, all kinds of banking operations necessary for the Central
Bank’s implementation of its main duties;
- it conducts
foreign exchange regulation, including operations to buy and sell
foreign exchange, and establishes the procedure for effecting
settlements with foreign countries;
- it organises and exercises
foreign exchange control on its own and through authorised banks in
accordance with the laws of the Russian Federation;
- it
participates in making Russian Federation balance of payments
forecasts and organises the drafting of the Russian Federation’s
balance of payments;
- it analyses and forecasts the state of the
Russian Federation’s economy as a whole and by region,
concerning specifically monetary, credit, foreign exchange, financial
and price relations, publishes the corresponding materials and
statistical data and performs other functions in accordance with
federal laws.
The Bank of Russia co-ordinates and regulates settlement relations in Russia and establishes the rules, forms, deadlines and standards for non-cash settlements obligatory for all legal entities and natural persons. The forms of non-cash settlements are determined by the Civil Code of the Russian Federation.
The principal forms of non-cash settlements today are payment orders and, to a lesser extent, payment requests (for collection). Letters of credit and cheques are used on a small scale.
A part of settlements is effected by legal entities and private individuals using payment cards, which are gaining ever wider acceptance.
The Bank of Russia is making efforts to ensure the effective and uninterrupted functioning of the settlements system and enhance its reliability.
Non-cash settlements are effectuated through correspondent accounts opened with the Bank of Russia, correspondent accounts opened by credit institutions with one another, correspondent accounts opened with non-bank settlement credit institutions and through the system ofintrabank settlements, using inter-branch settlement accounts.
Russian legislation accords the Bank of Russia a special place in the country's payments system. The Bank of Russia not only ensures general guidance of the payments system and provides the methodology and organisation of settlements, but also directly participates in this system, effecting interbank settlements through its divisions.
The payments made through the Bank of Russia settlement network account for a large part of the payments turnover.
Every participant in the settlements effected through the Bank of Russia settlement network is awarded an identification code. The Bank of Russia keeps the Russian Federation Bank Identification Code Directory (BIC Directory), which contains the following data: the name of each credit institution participating in settlements and its bank identification code, correspondent account with the Bank of Russia and domicile.
The BIC Directory is regularly reviewed and updated.
The credit institutions located in the Russian Federation (resident credit institutions) and having the banking licence of the Central Bank of the Russian Federation open only one correspondent account with one of the Bank of Russia institutions (a cash settlement centre or operations department), which services them. The branches of credit institutions may have correspondent subaccounts to implement settlements and may not have such accounts. If they don't, they effect settlements through the correspondent account of their parent organisation or the subaccount of another branch.
Overall, the Russian payments system comprises about 1,400 resident credit institutions, more than 4,000 branches of credit institutions and nearly 1,200 subdivisions of the settlement system and it is the principal means of implementing the official monetary policy by the Bank of Russia.
Non-cash settlements of clients of credit institutions and their branches are effected from the bank accounts opened with these institutions. In special cases, stipulated by the law, legal entities may have accounts opened with Bank of Russia institutions.
Credit institutions and their branches with correspondent accounts and subaccounts with the Bank of Russia effect settlements for their clients for commodities, works and services and make tax and other compulsory payments and their own income payments to the budget and payments to the accounts of state extrabudgetary funds through the various divisions of the Bank of Russia settlement network.
As for the settlements between clients of one credit institution (branch), they are effected by writing off or entering funds to the clients' corresponding accounts, bypassing the correspondent account of the credit institution (or its branch's subaccount) opened with a Bank of Russia institution.
Settlements between the cash settlement centres of the regional divisions of the Bank of Russia, serviced by a single computer centre, on transactions of credit institutions (or their branches) and on their own transactions are effected through the accounts opened specially for this purpose.
The correctness of settlements effected by the cash settlement centres is confirmed by the concurrence of the initial and reply turnovers in the process of confirmation, that is by comparing each reply entry with the initial one.
Payments are effected if there are funds in the correspondent accounts of credit institutions or subaccounts of their branches and within the amount of these funds. If a credit institution (or its branch) has not enough funds to meet all claims made on it, funds are written down from its correspondent account or from the subaccount of its branch to effect payments for its clients and its own payments in the order established by the Civil Code of the Russian Federation. In this case, documents are put into the file of unpaid settlement documents, attached to the correspondent account of the credit institution or the subaccount of its branch.
Settlements effected through the Bank of Russia settlement network are based not only on paper, but also electronic payment documents. These are the so-called intra- and interregional electronic settlements. The latter are regulated by the Provisions on Inter-Regional Electronic Settlements Effected through the Bank of Russia Settlement Network. The exchange of electronic documents through the Bank of Russia settlement network is regulated by the Provision on the Rules of Exchange of Electronic Documents between the Bank of Russia, Credit Institutions (Branches) and Other Clients of the Bank of Russia in Effecting Settlements through the Bank of Russia Settlement Network, adopted in March 1998.
The divisions of the Bank of Russia settlement network participate in electronic settlements as the bodies registering and supervising payments.
Credit institutions, their branches and other clients of the Bank of Russia that have correspondent or other accounts with the divisions of the Bank of Russia settlement network may use electronic settlements. This helps accelerate money turnover and reduce the amount of funds in settlements.
The term "electronic payment document" (EPD) is used in effecting electronic settlements in the Bank of Russia settlement network. The EPD is a document that serves as a legal basis for conducting operations with the accounts of credit institutions (branches) and other clients of the Bank of Russia, opened with a Bank of Russia institution, bearing an electronic digital signature and having equal legal force, stipulated in an agreement with the Bank of Russia, with paper based payment documents signed by the authorised persons with their own hand and stamped.
At present the electronic payment documents presented for execution to a Bank of Russia institution must contain the requisites in accordance with which operations with accounts are conducted. Two kinds of EPD may be exchanged:
—full-format EPD containing all requisites of a payment document, including textual requisites;
-abndged-format EPD containing the requisites necessary for conducting operations with accounts in a Bank of Russia institution.
The transfer of funds using fall-format EPD does not require accompanying payment documents on paper, while the transfer of funds using abndged-format EPD must be accompanied by an exchange of paper based payment documents, filled out in accordance with the established procedure.
During 1999 the Bank of Russia plans to phase in a paperless technology in its settlement system, using full-format electronic payment documents only in the exchange of electronic documents between Bank of Russia institutions and between the Bank of Russia and credit institutions.
After January 1,1998, the Bank of Russia charges a fee for its settlement services. Some kinds of settlement operations are conducted by the Bank of Russia free of charge.
Interbank settlements effected through correspondent accounts opened by credit institutions with one another play a part in the general payment turnover.
The rules of settlement operations with correspondent accounts of credit institutions opened with other credit institutions are formulated in the Bank of Russia Provisions on Effecting Non-Cash Settlements by Credit Institutions in the Russian Federation, which came into effect in 1998.
The operations conducted with correspondent accounts of correspondent banks are divided into two types: operations to service clients and own interbank operations.
The development of correspondent relations depends on various factors, such as mutual payment flows, price and demand in the credit market, the possibility of participating in trading in the regional government securities markets and on currency exchanges and the risk levels.
Specifically, settlements in correspondent relations are effected with credit institutions in CIS and other countries.
Settlements through clearing institutions are one of the means of interbank settlements.
The development of clearing settlements depends on the financial condition of credit institutions and the state of the money markets. Eight settlement credit institutions have been granted permanent licence as clearing houses.
Clearing operations are based on a clearing model requiring the participating banks to make preliminary deposits in their accounts with the clearing institution.
Nearly 2,000 credit institutions and their branches and other corporate clients effect settlements through non-bank clearing institutions.
The Bank of Russia has a decisive role to play in elaborating the principles of organising clearing operations and monitoring compliance with these principles.
Intrabank settlements are gaining acceptance. They include settlements between a head office of a credit institution and its branches and between branches of a credit institution. The procedure for conducting settlement operations with inter-branch settlement accounts in Russia is established by the Bank of Russia Provisions on Conducting Non-Cash Settlements by Credit Institutions in the Russian Federation.
A mid-term strategy for the development of Russia's payments system was elaborated in 1996. It sets forth as the main objectives of the reform of the system further modernising settlements, upgrading banking technologies, introducing new instruments of payment, raising the standard of services provided to credit institutions and other organisations and creating conditions for liquidity management.
To raise the banking technology of implementing settlements onto a qualitatively new level, new methods are being developed, new rules and regulations are being enforced, new technologies are being introduced and new organisational principles