Перевод английских текстов различной тематики
ILLUSTRATION 4 The Use of Debit and Credit Memoranda
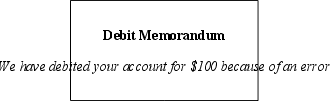
Situation — the buyer finds a $100 overstatement in an invoice from the seller


Debits the account payable Credits the account
to the seller for $100 and sends receivable from
the debit memorandum the buyer for $100
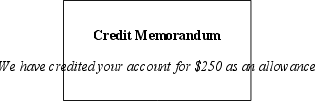
Situation — the seller agrees to give a $250 allowance to the buyer for defective goods
Debits the account payable Credits the account receivable
to the seller for $250 from the buyer for $250
and sends the credit memorandum
The debit memorandum in Illustration 4 is based on a case in which buyer initially records an invoice as an account payable and later discovers an error by the seller that overstated the total bill by $100. The buyer corrects the balance of its liability and formally notifies the seller of the mistake with debit memorandum reading: “We have debited your account for $100 because of an error.” Additional information is also provided about the invoice, its date, and the nature of the error. The buyer sends a debit memorandum because the correction debits the account payable to reduce its balance. The buyer’s debit to the payable is offset by a credit to the Purchases асcount.
When the seller receives its copy of the debit memorandum, it records a credit to the buyer’s account receivable to reduce its balance. An equal debit recorded in the Sales account. Neither company uses a contra account because the adjustment was created by an error.
In other situations, an adjustment can be made only after negotiations between the buyer and the seller. For example, suppose that a buyer claims that some merchandise does not meet specifications. The amount of the allowance to be given by the seller can be determined only after discussion. Assume that a buyer accepts delivery of merchandise and records the transaction with a $750 debit to the Purchases account and an equal credit to Accounts Payable. Later, the buyer discovers that some of the merchandise is flawed, and can be sold only if it is marked down substantially. After a phone call and brief negotiations, the seller agrees to grant a $250 allowance against the original purchase price.
The seller records the allowance with a debit to the Sales Returns and Allowances contra account and a credit to Accounts Receivable. Then, the seller formally notifies the buyer of the allowance with a credit memorandum. A credit memorandum is used because the adjustment credited the receivable reduce its balance. When the buyer receives the credit memorandum, it debits Accounts Payable and credits Purchases Returns and Allowances. Contra accounts provide both companies’ managers with useful information about the allowance.
Inventory Shrinkage
Merchandising companies lose merchandise in a variety of ways, including shoplifting and deterioration while an item is on the shelf or in the warehouse. These losses are called shrinkage.
Even though perpetual inventory systems track all goods as they move into and out of the company, they are not able to directly measure shrinkage caused by shoplifting or thefts by employees. However, these systems allow the accountant to measure shrinkage by comparing a physical count with recorded quantities.
Because periodic inventory systems do not identify quantities on hand, they cannot provide direct measures of shrinkage. In fact, all that they can determine is the cost of the goods on hand and the goods that passed out of the inventory. The amount that passed out includes the cost of goods sold, stolen, or destroyed. For example, suppose that shoplifters took merchandise that cost $500. Because the goods were not on hand for a physical count, the ending inventory’s cost is $500 smaller than it would have been. Ultimately, the $500 is included in the cost of the goods sold.
Alternative Income Statement Formats
Within the framework of generally accepted accounting principles, companies have flexibility in selecting a format for their financial statements. In fact, practice shows that many different formats are used. This section of the chapter describes several possible formats that Meg’s Mart could use for its income statement.
 illustration
5
Classified Income Statement for
Internal Use
MEG’S MART
Income Statement
For Year Ended December 31,19X2
Sales. $321,000
Less: Sales returns and allowances $ 2,000
Sales discounts ….... . . ….... 4,300 6,300
Net sales $314,700
Cost of goods sold:
Merchandise inventory, December 31,19X1 . . $ 19,000
Purchases $235,800
Less: Purchases returns and allowances …. $1,500
Purchases discounts 4,200 5,700
Net purchases $230,100
Add transportation-in 2,300
Cost of goods purchased 232,400
Goods available for sale …... $251,400
Merchandise inventory, December 31,19X2 . . 21,000
Cost of goods sold 230,400
Gross profit from sales . $ 84,300
Operating expenses:
Selling expenses:
Depreciation expense, store equipment …. $ 3,000
Sales salaries expense 18,500
Rent expense, selling space . 8,100
Store supplies expense 1,200
Advertising expense